Coursera
MOOC / Non-credit
0
Kalman Filter Boot Camp (and State Estimation)
About this course
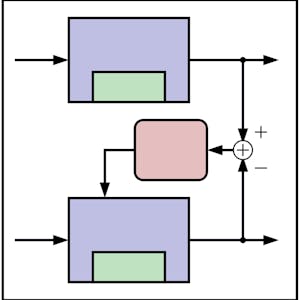
Introduces the Kalman filter as a method that can solve problems related to estimating the hidden internal state of a dynamic system. Develops the background theoretical topics in state-space models and stochastic systems. Presents the steps of the linear Kalman filter and shows how to implement these steps in Octave code and how to evaluate the filter’s output.
A
82/100
CourseAsk score
- What the provider tells you
- 31/45
- Who stands behind it
- 35/35
- How complete the listing is
- 16/20
Scores how much the provider publishes and who stands behind it — not how well it is taught.
What you'll learn
- understand the concept of the Kalman filter
- implement the Kalman filter in Octave
- evaluate the output of the Kalman filter
- grasp the principles of state-space models and stochastic systems
Course objectives
- to introduce the Kalman filter as a solution for state estimation
- to develop theoretical knowledge in stochastic systems
- to provide hands-on experience with Octave coding
Machine Learning
#data analysis
#control systems
#signal processing
#dynamic systems
#octave
#kalman filter
#state estimation
#state-space models
#stochastic systems
$49.00
Price shown by Coursera — confirm on their site.
Enroll on CourseraYou'll be redirected to Coursera to complete enrollment.
- Listed & compared by CourseAsk
- English · 0

 Udemy

 edX

 Coursera



Compared on these lists
Where this course ranks against the alternatives.